
Today’s Numbers
~$103 (Brent on Monday morning, off a weekend spike above $105) · 5.24% (US 10-year Treasury yield at Friday’s close) · 74.5% (Polymarket odds of a Fed rate hike in December). Washington spent the weekend announcing a Russia–Ukraine energy truce and a Russian diesel deal, while the Houthis hit Saudi Arabia’s capital. Oil moved a dollar or two on both. The number that barely moved is the one that decides the week: the market’s conviction that the Fed’s next move is up.
Wall Street closed Friday on a record week. The S&P 500 rose 0.6% to 7,811.54, just shy of Tuesday’s all-time high, even as the 10-year yield climbed to 5.24%. Then the weekend delivered two geopolitical shocks pointing in opposite directions.
The first was a peace discount. On Friday, President Trump said Russia would immediately supply more than 300,000 tonnes of diesel, with 500,000 more in November and a million after that. On Sunday he announced that Russia and Ukraine had agreed to stop hitting each other’s energy facilities. Kyiv said it was still waiting for details; Moscow said nothing. Brent fell 1.3% to $103.35 in early Asian trade, and ICE gasoil dropped 3%.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
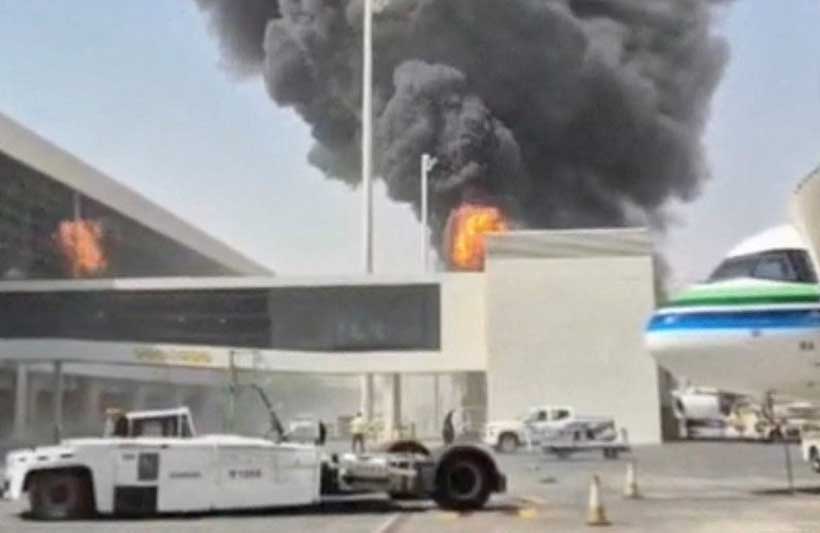
The second was a war premium. On Saturday a strike blamed on the Houthis hit Riyadh’s King Khalid International Airport, killing at least 12 people, including an American, and wounding 309. The airport was hit again on Sunday, and Dammam’s airport was attacked that night. Trump said the US was weighing joining Saudi strikes on the Houthis. In Tehran, officials called Washington’s latest reply on reopening Hormuz “insufficient”. Two more tankers were hit over the weekend, one off Oman’s Sohar anchorage and one transiting Hormuz. By early morning in New York, Yahoo Finance had Brent back near $106 on reports that Russia had struck Ukrainian power plants after all.
The Mechanism
The weekend’s real story is which barrel matters. For decades crude was a fair proxy for the fuels that drive inflation. That link has broken. Energy Aspects’ Amrita Sen notes that refined products have traded at double the price of crude in recent months, and that since May the 10-year Treasury yield has tracked diesel more closely than crude for the first time on record. Damage to Middle Eastern and Russian refineries explains the gap: US diesel is about 71% above a year ago, crude about 56%.
Read the weekend through that lens. The Russian diesel deal is not an oil story; it is an attempt to lean on the bond market through the fuel that feeds trucking, farming and factory prices. It is also small. The first 300,000 tonnes is about 2.25 million barrels, against global diesel demand the IEA puts near 29 million barrels a day. And as one energy economist told the AP, Russian diesel sent to the US is diesel withheld from someone else. The price effect is a reshuffle, not new supply.
The Gulf side works the other way. Kpler data cited by CNBC put Hormuz crude flows at 8.5 million barrels a day in the week to 7 October, roughly 40% below normal, after the most ship attacks of the war in the prior week. Goldman Sachs now estimates a war risk premium of just over $20 a barrel in Brent and lifted its December forecast to $90. Strip out that premium and oil is not the problem. Keep it, and every Houthi strike on Saudi soil is a bid under diesel and, through diesel, under yields.
Why It Matters
Markets are pricing two different worlds at once. Equities are pricing calm: the VIX sat near 14.8 on Friday and S&P futures edged higher on Monday morning as the bull market turned four. Rates are pricing a fight. Polymarket puts a Fed hike at only 16.5% for the 28 October meeting but 74.5% for December, and Friday’s Michigan survey lifted one-year inflation expectations to 4.7%. Both cannot be right for long, and this week’s data decides which gives.
The diplomacy has a price too. Last month Trump signed a sanctions law imposing steep tariffs on the biggest buyers of Russian energy. On Friday Washington became a buyer of Russian diesel, and the Treasury temporarily waived sanctions on Russia’s energy sector to let it flow. Moscow gains a revenue stream and, more valuable, a precedent: energy as a bargaining chip with the White House rather than a target of it. That lands awkwardly in Europe, which adopts a record 1,646 Russia listings this week and still cannot agree to touch the €185bn at Euroclear.
The Gulf talks offer little offset. Vice President Vance has softened the zero-enrichment demand to a “meaningful” reduction, but Tehran says it may dilute its high-enriched uranium in later talks while never abandoning enrichment. Its security chief, Mohsen Rezaei, has also threatened “cables, data centers, AI facilities” in the region if heavy fighting resumes. Until Hormuz flows normalise, Goldman’s $20 premium is the floor under the inflation trade, not the ceiling.
Watch For
Wednesday’s US consumer-price report for September. The test is transport and energy services, where diesel shows up first. A hot print likely pushes the 10-year back through last week’s 5.3% peak and makes a December hike the consensus. A cool one gives the peace headlines room to work. Before that, the US cash Treasury market is shut today for Columbus Day, so bonds digest the weekend on Tuesday, the same day JPMorgan, Goldman Sachs and Citi open earnings season. Retail sales follow Thursday, alongside the EU leaders’ summit in Brussels on 15–16 October. And watch whether the energy ceasefire survives the week: if Russian strikes on Ukrainian power plants are confirmed, the peace discount is gone, and only the war premium is left.