
Twenty-Four Hours in October
On 1 October Washington told Europe to release 120 million barrels of diesel from its emergency stocks over six months, or face a ban on American diesel exports to Europe. The next day, the G7 agreed to release 100 million barrels of diesel and other products over four months, with “a front-loaded substantial diesel release within the first 20 days” — a window that closes around 22 October.
The speed is the story. A refiner’s threat moved the world’s seven largest advanced economies in a day. Half a century ago, the countries that could make the G7’s predecessors jump were the oil producers of the Gulf. This autumn the leverage belongs to whoever has spare refining capacity — the United States, India, South Korea and China — and the most exposed buyer is a Europe that spent two decades closing its refineries.
How Europe Ran Short of the Middle
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
Diesel and jet fuel are “middle distillates”, the part of the barrel that runs trucks, tractors, ships and planes. Europe has been short of them for years, importing the difference. After its 2023 embargo on Russian products, it replaced Russian diesel with cargoes from the Middle East, India and the United States. The Hormuz crisis then knocked out the Gulf leg: the IEA’s September report puts Gulf exports of refined products and LPG about 60% below February levels, against roughly 45% for crude.
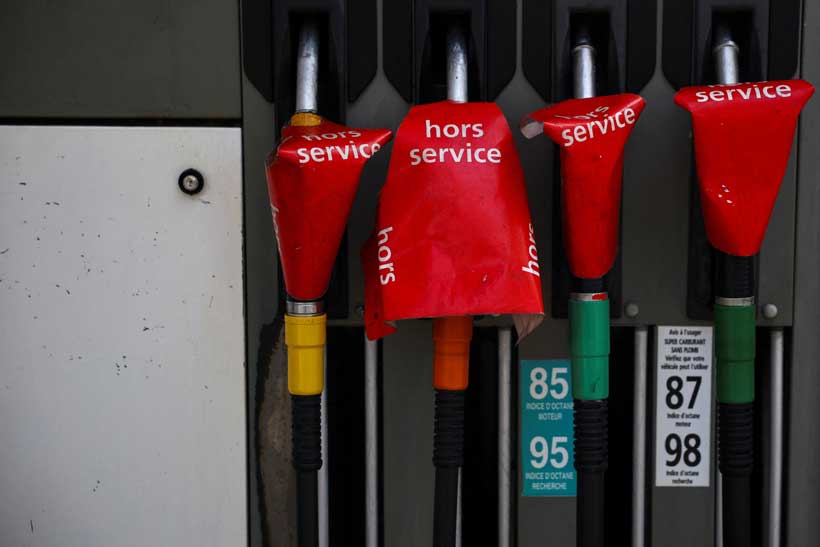
The gap has been filled by America. The US now supplies about 32% of the EU’s diesel imports from outside the bloc, up from 17% last year, and 57% of North-West Europe’s. France gets 36% of its diesel imports from the US; the UK 26%. Both closed refineries recently — Grandpuits and Donges in France, Grangemouth in Scotland — and the EU as a whole lost more than 370,000 barrels a day of refining capacity in 2025, as MD has reported. European diesel prices have more than doubled this year.
Why the Barrel’s Middle Is Now Its Power
The common reading of this crisis is that the world is short of oil. It is more precisely short of the capacity to turn oil into the fuels economies run on. The IEA estimates that lost Middle Eastern diesel output is three times the size of lost Russian supply. European diesel refining margins — the gap between the price of crude and the price of diesel — hit a record $74 a barrel in July, according to Business Standard. That margin is the modern equivalent of the 1973 price shock: a scarcity rent, captured not by those who own the crude but by those who own the refineries.
And refiners answer to governments. Every major exporter has used export policy as an instrument this year. China ordered its refiners to halt fuel exports in the first weeks of the war, eased them by July, and now faces analysts’ warnings that Beijing could cut clean-product exports to around 1.2 million tonnes a month in the fourth quarter. South Korea capped fuel exports at last year’s monthly levels in March. Russia, Europe’s former supplier, has banned diesel exports through 31 October. India is the exception that proves the rule: Reliance pushed diesel loadings for Europe to a ten-month high in July, but its cargoes go to whoever pays most, and August flows depended on whether Asian buyers outbid Europe.
The United States, now the world’s largest diesel exporter at about 1.6 million barrels a day, has shown how the weapon works. On 22 September Trump said he had “called for” a ban, backed by farm-state Republicans facing the midterms. The next day the White House said nobody was considering a flat ban. Before the war, US diesel exports ran at 1.1–1.2 million barrels a day; the extra 400,000 a day is, in effect, Europe’s safety margin, and it can be switched off by executive order. A week later the threat was back, aimed at Paris and Berlin, and within 24 hours Europe was opening its tanks. The ban never had to happen. That is what leverage looks like.
Europe’s exposure is largely self-inflicted. It treated refining as a sunset industry to be managed down, not a strategic asset, and it has now spent its buffer at someone else’s request: in March most of Europe’s contribution to the IEA release was refined products and industry stocks rather than crude. As MD has argued, refining capacity now matters more than oil reserves — and Europe has neither in surplus.
The strongest objection is that fuel markets are global. A US ban would push up world prices and, eventually, American ones, which is why the oil industry and most economists oppose it. India sells to the highest bidder; Europe can always buy. All true — but “Europe can always buy” means Europe pays whatever the refiners and their governments choose to make it pay, bidding, in one analyst’s words, “against the Mediterranean, Latin America and West Africa for the same limited pool of barrels”. Leverage does not require a ban. It requires a credible threat and a buyer with no alternative. The first week of October showed both.
Three Winters for Diesel
Base case — threat and release (about 55%). The G7’s front-loaded diesel eases prices modestly into late October. Washington keeps the export-ban threat in reserve through the 3 November midterms and beyond, using it to extract further European releases. Diesel stays above €2 a litre through the winter, and European hauliers, farmers and airlines absorb a sustained cost premium. For business, this means budgeting for expensive distillates through the first quarter, not a short spike. The key assumption is that the threat stays a threat: a ban before the midterms would cost farm-state Republicans more in higher world prices than it saved them at home.
Downside — the export cascade (about 25%). Three restrictions land together: Beijing cuts fourth-quarter export quotas, Russia extends its ban beyond 31 October, and a cold snap pushes Washington into a partial ban. North-West Europe, the region most dependent on US cargoes, faces physical shortages rather than high prices, and governments move to rationing for freight and farming. The early warning is Moscow’s decision on its ban at the end of the month.
Upside — the Gulf comes back (about 20%). A US–Iran deal reopens Hormuz and Gulf refineries restart exports. Diesel falls faster than crude as margins collapse, and Europe gets a reprieve. The test is whether it uses it: keeping marginal refineries open, setting product-specific stock rules and treating refining as part of defence-industrial policy. Without that, the reprieve simply resets the clock to the next crisis.
Whoever Owns the Middle
Oil power has moved down the supply chain. The countries that refine — and decide when to export — now hold the leverage that producers held in 1973, and they have all shown this year that they will use it when their own voters demand it. Europe dismantled its refining base and banned its old supplier, and is now paying a strategic premium for both decisions.
Watch European diesel prices in the days after 22 October, when the G7’s front-loaded release ends, and Russia’s decision on its export ban due by 31 October. If prices rise again as the release tapers, the release was a payment, not a solution. In this crisis, the barrel’s middle is where the power is — and Europe no longer owns it.