
A Holiday Notice That Moved the Oil Price
On Wednesday, on the eve of China’s Golden Week holiday, PetroChina cancelled most of the gasoline and jet fuel cargoes it had committed for October, many of them agreed only in the previous fortnight. By Thursday, according to four people briefed on the decision, Chinese refiners had suspended fuel exports to everywhere except Hong Kong and Macau until further notice. There was no public announcement; the news leaked through traders.
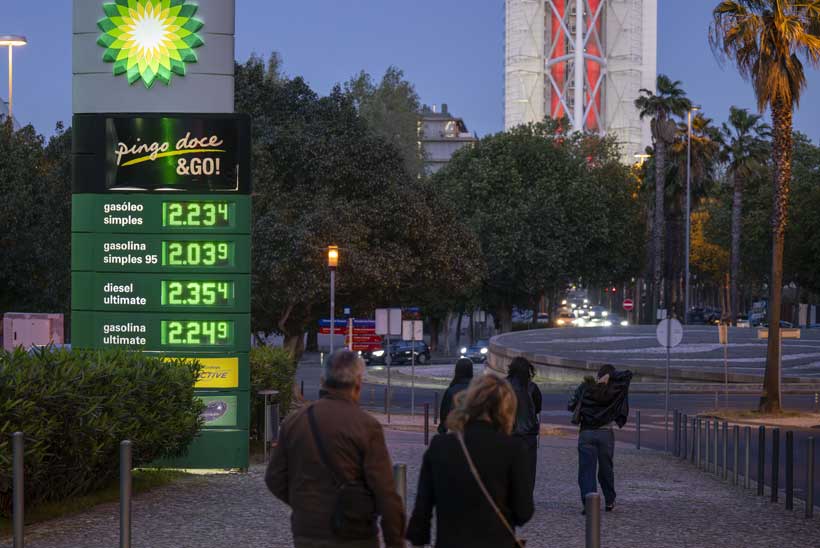
Markets reacted anyway. US crude turned an early loss into a rally to around $91.50, and diesel in Asia traded about $75 a barrel above the crude it is made from. In a fuel market already short of millions of barrels a day, a quiet instruction to Chinese refiners proved as powerful as an OPEC meeting. The question is what Beijing intends to do with that power.
From Swing Supplier to Self-Supplier
China has the world’s largest refining system, able to process roughly 18.8 million barrels a day. Its fuel exports have always been tightly managed through quotas, but in normal times they made China a reliable source of diesel, petrol and jet fuel for Asia. In 2024, by one estimate, China supplied a third of Australia’s jet fuel and about half of the fuel used by the Philippines and Bangladesh.
Stay ahead of the geopolitical week.
MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.
That role has been switched on and off all year. Beijing curbed exports in March as the Iran war closed Hormuz, then eased them in mid-July. In August China exported 6.01 million tonnes of oil products, up 12.7% on a year earlier. That surge drained its own tanks: by late September commercial gasoline stocks were at their lowest since 2011 and diesel stocks at their lowest since 2015.
Hoarding, Not Coercion — Which Is the Problem
The tempting reading is that Beijing is weaponising fuel, as Russia weaponised gas in 2022. The evidence does not support it. This halt is driven by domestic need, and part of that need was created in Washington.
Start with supply. Between a fifth and a quarter of China’s refining capacity sits in independent “teapot” refineries in Shandong province, whose business model depended on discounted Iranian crude. Since the United States reimposed its blockade of Iranian oil on 13 July, those barrels have dried up and the discount has turned into a premium. As Modern Diplomacy has reported, physical interdiction has achieved what a decade of sanctions could not: the teapots cannot sanction-proof this war. With independent refiners cutting runs and domestic demand recovering seasonally, China’s surplus of fuel to export has shrunk sharply.
Then look at the law. China’s Energy Law, in force since January 2025, made holding strategic reserves a legal obligation for state and private companies. China built crude stocks of roughly 1.1 to 1.2 billion barrels — about 100 days of import cover — before the war began. A state that thinks this way does not need a geopolitical motive to stop exporting fuel when its own tanks run low. Security comes first by statute.
But hoarding still creates leverage. Leverage does not require intent; it requires that others depend on your discretion. Here the record is instructive. When Beijing first banned exports in March, deepening Asia’s fuel shortage, it quietly kept diesel flowing to the Philippines and Vietnam, both rivals in the South China Sea. That undercuts the coercion story: a state bent on punishment would have starved Manila first. Yet it confirms the larger point. Supply was allocated by Beijing, cargo by cargo, rather than by price. As one analyst put it at the time: “China restricts supplies rather than coming to the rescue.” Neighbours have learned that Chinese fuel is available when China has spare product, and on China’s terms when it does not. That uncertainty is a form of power, even if no one in Beijing designed it as one.
The damage travels well beyond Asia, because fuel markets are connected by price, not by geography. China ships little diesel directly to Europe. But when Chinese barrels vanish from Asia, Asian buyers bid for Indian, Korean and Middle Eastern cargoes that would otherwise sail west. Europe was counting on the opposite: traders had expected Chinese refiners to add more than a million tonnes of diesel to international markets in September. Now the Indian refiners that have been filling Europe’s gap face a stronger pull from Asia. The halt also lands as Russia keeps its own diesel export ban in place until 31 October and Washington debates restrictions. Three of the world’s most flexible fuel exporters are putting their home markets first at the same time.
That is where inflation comes in. Diesel moves goods and powers farm machinery, so its price feeds directly into freight and food costs. US distillate stocks are already 14% below their five-year average. In Asia, which burns 38% of the world’s oil, the IMF had already raised its forecast for regional inflation to 2.6% this year, up from 1.4% in 2025, and named Sri Lanka, Bangladesh and Cambodia among the most exposed. A prolonged Chinese halt would push that figure higher.
The strongest objection is that this is temporary: a holiday-period pause by refiners guarding stocks, which will ease once inventories rebuild, as it did in July. Exports will probably resume in some form. But the pattern of this year — curb, ease, curb again, each time without warning — is itself the change. Analysts at Energy Aspects expect Beijing to hold clean-fuel exports to around 1.2 million tonnes a month in the fourth quarter, less than half of July’s 2.55 million tonnes. Even a “resumption” would leave Asia far shorter than before.
Three Ways the Next Quarter Could Run
Base case (around 55%) — exports return, but rationed. After Golden Week, Beijing issues a reduced quota in the region of 1.2 million tonnes a month. Asian diesel and jet margins stay near record levels, more Indian and Korean cargoes are pulled east, and Europe’s winter shortfall widens. No dramatic crisis follows, only a higher fuel bill everywhere. This rests on Gulf refineries continuing their slow recovery and no further loss of crude supply to the teapots.
Downside case (around 25%) — the halt runs through the winter. Inventories fail to recover because the teapots stay short of crude and winter demand rises. Russia extends its ban beyond October and Washington imposes even partial diesel export limits. With China, Russia and the US all restricting at once, the poorest Asian importers ration fuel — Bangladesh and Sri Lanka first — and regional inflation overshoots the IMF’s forecast. In this scenario, Beijing’s allocation of whatever it does export becomes openly diplomatic: who gets cargoes, and on what terms, becomes a question for foreign ministries rather than traders.
Upside case (around 20%) — a deal refills the teapots. A US-Iran settlement lifts the blockade, Iranian crude flows back to Shandong, and Gulf refineries recover faster than expected. Beijing issues a generous quota and presents it as a contribution to regional stability. Prices ease, but the lesson remains: relief arrived because China chose to give it.
Supply on Beijing’s Terms
China is not yet using fuel as a weapon. It has done something that may matter more in the long run: it has made clear, through law, stockpiles and repeated export halts, that its fuel security outranks its role as the region’s supplier. In a market this tight, that ranking is itself leverage. Asia, and indirectly Europe, now buys Chinese fuel at Beijing’s discretion rather than at a market price.
Watch the first export quota Beijing issues after Golden Week ends on 7 October. A figure near 1.2 million tonnes a month confirms rationing as the new normal. Anything lower means the winter shortage is no longer a forecast.
For two decades Asia treated China’s refineries as a common resource. This week it learned they were always national ones.